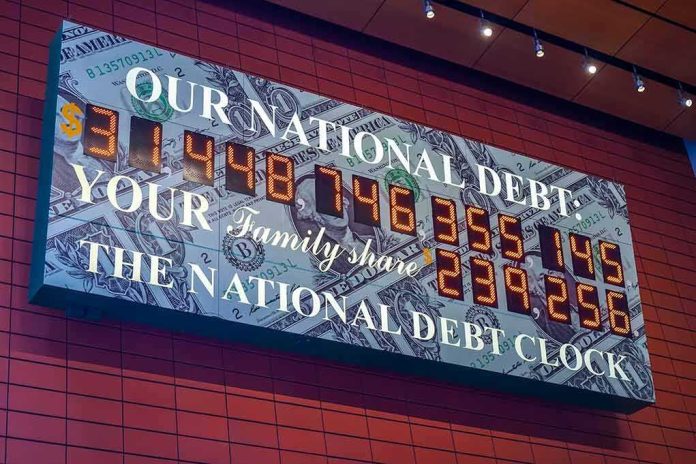
One month into the new fiscal year, Washington burned through $404 billion more than it took in—and the bill for interest alone rivaled the Pentagon’s cash burn.
Story Snapshot
- Treasury reported a $404.1 billion deficit for October 2026, the first month of the fiscal year.
- Outlays jumped to about $773 billion, up sharply from October a year earlier.
- Defense outlays neared $84 billion for the month; interest costs approached $100 billion.
- The Congressional Budget Office (CBO) independently estimated a $409 billion shortfall.
October’s Red Ink Set The Tone For The Year
The United States Department of the Treasury reported a $404.1 billion deficit for October 2026. That is the first month of the government’s new fiscal year, and it started deep in the red. The Congressional Budget Office put its own estimate at $409 billion, which lands close to Treasury’s figure and confirms the scale. The gap from October 2025 widened by well over $100 billion, showing a notably weaker opening month than last year’s start.
Total outlays hit about $773 billion in October, up from roughly $689 billion in the same month last year, while revenues lagged behind that pace. Defense spending stood out. Department of Defense military programs drew about $84.2 billion during the month, a heavy slice of the total. Interest on Treasury debt also weighed on the ledger. Treasury’s data show gross interest near $98.6 billion for October, with some outlets citing nearby but not identical measures.
Defense And Interest: The Twin Drains
Defense outlays in October reached a level that shapes the month’s story all by itself. The Pentagon’s drawdown touched about $84 billion, which tracks with active contracts, operations, and procurement cycles that often cluster in early fiscal months. At the same time, the meter on interest kept spinning. Treasury’s gross interest line near $98.6 billion tells a clear truth: the cost of past borrowing now rivals a major cabinet department’s entire monthly outlay.
Claims that 28 percent of taxes go to interest refer to a rolling year share, not a single month’s slice. Still, the October bill shows why that line resonates. Higher rates meet higher debt, and the math boxes in choices. As the Government Accountability Office has warned for years, large interest costs squeeze room for core programs and national defense. Dollars that go to interest cannot go to border security, veterans, or research.
Receipts Lag While Outlays Race Ahead
The deficit widened because spending grew faster than income. Outlays climbed to about $773 billion, while receipts did not keep pace with that surge. Year-over-year, the October deficit moved from roughly $284 billion to $404 billion, a jump that dwarfs normal month-to-month noise. The Committee for a Responsible Federal Budget noted that some payments shifted into October from November, but even after timing adjustments, the gap stayed very large. That underlines pressure that is not just a calendar trick.
The CBO’s estimate running $5 billion above Treasury’s final tally is typical and comes from different methods and timing conventions. For readers tracking debt supply, Fortune reported that Treasury borrowed more than $100 billion per week during October, a pace that links directly to the month’s funding needs and the refinancing calendar. Markets can absorb a lot, but price matters. When rates rise, interest costs rise, and the cycle tightens the vise.
What The Numbers Signal For Policy
These facts point to a basic, common‑sense view. A country that spends far more than it takes in will drift toward a future where interest eats the budget. That is not theory. It is October in black and white. A serious plan would set guardrails on spending growth, protect core defense readiness, and lock in pro‑growth tax policy that drives revenue through a larger economy rather than higher rates on a shrinking base. That is the path that aligns with fiscal discipline and national strength.
Label the priorities plainly. Keep the military lethal, but demand value and timing discipline on big buys. Right-size the safety net to what the economy can support, with tougher anti-fraud controls and work-first designs. Cap the annual growth rate of discretionary spending below the economy’s growth rate until debt stabilizes. And stop pretending interest is a harmless line item. October shows it is now a head-to-head rival with defense. If we will not choose, the math will choose for us.
Sources:
zerohedge.com, fiscaldata.treasury.gov, cbo.gov, tradingeconomics.com, gao.gov